Author

admin

Browsing

Fast-food restaurants are losing breakfast customers to convenience stores.

Morning meal traffic to fast-food chains rose 1% in the three months ended in July, while visits to food-forward convenience stores climbed 9% in the same period, according to market research firm Circana.

“Over the long run, convenience stores have taken share, really at foodservice overall, but the morning meal has been their strong suit,” David Portalatin, Circana senior vice president and foodservice industry advisor, told CNBC, noting the trend has largely been driven by what the group calls “food-forward convenience stores.”

For decades, McDonald’s and its rivals have tried to lure consumers away from home to eat their early morning offerings, betting that convenience and unique items will win over diners.

While fast-food chains have made some inroads, 87% of what consumers eat and drink in the morning comes from their own refrigerators or pantries, according to Portalatin. That leaves plenty of opportunity for fast-food chains — and anyone else who wants a slice of the breakfast pie.

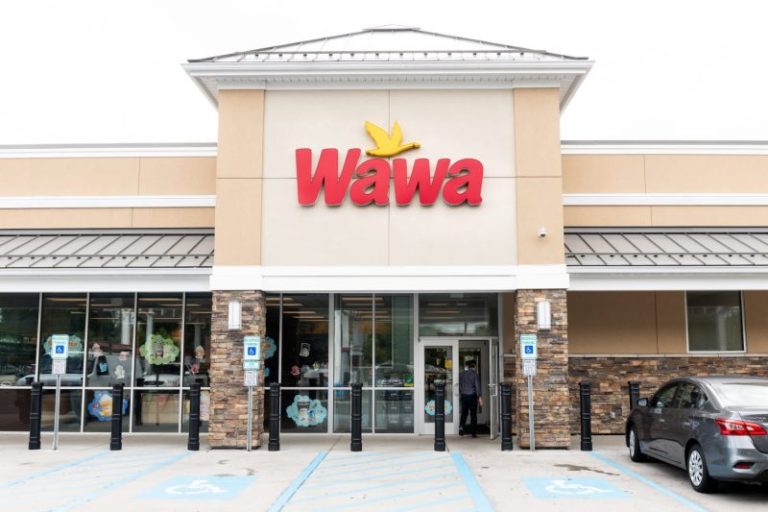
Before the pandemic, fast-food chains started seeing a new rival for their breakfast customers: convenience stores. Regional chains like Wawa in the Northeast and Casey’s General Store in the Midwest were expanding their reach and investing in their foodservice options, taking pages from the fast-food companies’ own playbooks.

For a time, lockdowns and the shift to hybrid work reversed those market share gains. But in the three months ended in July, food-forward convenience stores once again gained the upper hand in the battle to serve consumers breakfast, according to Portalatin.

Circana separates food-forward convenience stores like Buc-ee’s and Sheetz from the broader industry, although more chains may soon fit under that umbrella. 7-Eleven, the biggest convenience, or c-store, in the U.S., is planning to invest more in its prepared foods business, inspired by the success of its Japanese business. C-store chain RaceTrac on Wednesday announced that it’s buying Potbelly for about $566 million, although it’s unclear what its plans for the sandwich chain include beyond expanding its footprint.

In recent years, more diners have been watching their budgets, conscious of rising menu prices and a tight job market.

Year-over-year morning traffic to fast-food chains has fallen every quarter for the last three years, according to data from Revenue Management Solutions, which advises restaurants on how to increase sales and profits. In the second quarter, fast-food breakfast visits fell 8.7%.

To see the struggles, look no further than McDonald’s, which dominates the quick-service breakfast category.

″The breakfast daypart is the most economically sensitive daypart, because it’s the easiest daypart of a stressed consumer to either skip breakfast or choose to eat breakfast at home,” McDonald’s CEO Chris Kempczinski said on the company’s earnings call in late July. “And we, as well as the rest of the industry, are seeing that the breakfast daypart is absolutely the weakest daypart in the day.”

McDonald’s morning visits accounted for 33.5% of its traffic in the first half of 2019 but fell to 29.9% in the first half of 2025, according to Placer.ai data. To try to drum up traffic, the chain has included breakfast items in its new Extra Value Meals, including a deal for a Sausage McMuffin with Egg with a hash brown and a small coffee for $5.

To reverse breakfast’s slide, fast-food chains are taking hints from their competition. After years of convenience stores looking to fast-food chains for ideas on how to grow prepared food sales, from installing ordering kiosks to new menu items, the dynamic has flipped.

″[Quick-service restaurants] are looking at late-night sales and early morning sales, and they are directly looking at convenience stores and saying, ‘What is working? How can we bring that to our stores?’” National Association of Convenience Stores spokesperson Jeff Lenard told CNBC.

Prepared foods have offered a lifeline for convenience stores as demand for gasoline, tobacco and lottery tickets has fallen over time. The industry’s overall foodservice sales reached $121 billion in 2024, according to data from the NACS.

Most customers visit the gas pump during the morning and evening rush hours, on their way to and from work, presenting the perfect opportunity for c-stores to sell them breakfast or dinner. This year, 72% of consumers surveyed by InTouch Insight said they saw c-stores as a real alternative to fast-food chains, up from 56% a year ago and 45% two years ago.

Broadly, the c-stores that have focused on fresh food have been winning over more customers.

For example, Wawa has seen its customer base grow by 11.5% since 2022, while fast-food chains McDonald’s, Burger King and Wendy’s have seen their combined customer base shrink 3.5% in the same time, according to data from Indagari, a transaction data analytics firm.

The majority of 1,170 respondents to an InTouch Insight survey for CNBC said that they have purchased made-to-order breakfast from a c-store in the morning in the past three months. Forty-eight percent of respondents said that when they choose breakfast from a convenience store, they are replacing a visit that they might otherwise make to a fast-food restaurant like McDonald’s or Dunkin’.

Buying coffee and breakfast from a c-store likely won’t be cheaper than making it at home. But consumers perceive it as “good bang for their buck,” according to Sarah Beckett, vice president of sales and marketing for InTouch Insight.

Plus, c-store customers get a wider breadth of options. In addition to coffee, gas stations sell energy drinks, protein shakes and yogurt smoothies. And customers can pick up a granola bar or banana to accompany their breakfast sandwich. Fast-food chains lack that kind of variety.

But above all, what matters to consumers is the food itself.

“While [a] convenience store broadly does have some tailwind from being a lower price point, the ultimate differentiator, and what’s really going to set apart the winners from losers, is that quality aspect of it,” Circana’s Portalatin said.

Brady Caviness, a 33-year-old account executive at Bailiwick who lives in Minneapolis, told CNBC that he indulges in a breakfast pizza from Casey’s General Store when he’s traveling. If he’s back home, where there isn’t a Casey’s nearby, he’ll stop by McDonald’s, Dunkin’ or Starbucks if he’s in the mood to buy his breakfast.

The Iowa-based chain is the country’s third-largest c-store chain and claims to be the fifth-largest pizza concept based on its number of locations. Casey’s reported same-store sales growth of 5.6% for its prepared food and dispensed beverages for the three months ended July 31.

Like Taco Bell’s Mexican Pizza, Casey’s breakfast pizza, topped with cheese, scrambled eggs and a choice of bacon, sausage or vegetables, has grown a cult following since its launch in 2001.

“I think Casey’s is kind of a unique thing,” Caviness said. “My whole life, I’ve had the Egg McMuffins.”
This post appeared first on NBC NEWS

Perth, Australia (ABN Newswire) – Locksley Resources Ltd (ASX:LKY,OTC:LKYRF) (FRA:X5L) (OTCMKTS:LKYRF) is pleased to advise that the Company is advancing a significant expansion to its exploration program, given the substantial increase in its landholding abutting MP Materials and identification of additional historical workings across the project areas.

Highlights

– Post the substantial expansion of Locksley’s claim portfolio, the Company has determined that it will significantly increase the scale and accelerate the pace of its exploration program

– The expanded program will be focused upon exploring both the existing antimony and rare earths elements prospects, plus targeting additional commodities that have been identified on Locksley’s larger land holding

– Post the evaluation of recent field activities Locksley will provide the market with a detailed outline of the expanded exploration program

– A substantial historical shaft has been discovered during a surface geological and structural mapping campaign recently undertaken at Mojave

– Shaft depth and the extent of underground workings is being evaluated, but is estimated at >15m and the Company is determining the composition of the commodities that were mined

– Vein orientation striking NNE, similar to that at the Desert Antimony Prospect, supports the developing geological interpretation of multiple NNE striking structures across the Mojave Project

– Grab samples collected from the prospect being submitted for laboratory analysis

– Locksley hosts broker and analyst site visit at Mojave

Expanded and Accelerated Exploration Program

Given the combination of the significant increased land holding and the potential for other commodities to be present (as confirmed from the discovery of an additional shaft on the Mojave Project), Locksley has elected to expand its exploration activities. The Company has commenced the planning process for these expanded activities and will advance these undertakings in the coming weeks.

Geological Mapping & Historical Mining

Locksley has recently undertaken multiple rounds of field mapping to increase the understanding of the Mojave Project. During the most recent field mapping campaign, Locksley’s geologists have discovered a historical shaft in the core of the North Block whilst mapping the area for REE potential.

The extent of the workings seen in the vicinity indicates that a substantial shaft (estimated potentially >15m depth) has been mined. Initial grab sampling has been completed with the aim of determining what commodities were extracted. These newly discovered historical workings provide a new exploration target (named Hendricks) for Locksley.

The broader geological mapping has been completed, and the prioritised mapping of the NE and SW extensions from the Desert Antimony Mine, the western limits of the North Block claims (which lie due north of the Mountain Pass Mine) and the North Block REE target (where the shaft was discovered). The field geologists are compiling their mapping data and will incorporate the findings into the broader geological understanding and targeting for a follow up field sampling campaign.

Broker and Analyst Site Visit

Locksley hosted a site visit for brokers and analysts at the Mojave Project on Saturday, 13th September, following the substantial increase in its landholding abutting MP Materials. The visit provided key stakeholders with first hand exposure to the scale of Locksley’s expanded tenure and the planned drilling at the Desert Antimony Mine and El Campo. The field trip underscored the strong geological potential across the project portfolio and highlighted the Company’s commitment to advancing exploration and development activities in one of the most strategic critical mineral regions in the United States.

Pat Burke, Chairman of Locksley Resources, commented:

‘The substantial expansion of our landholding within the Mojave Critical Minerals Corridor marks a pivotal step in Locksley’s growth. The site visit with brokers and analysts provided an excellent opportunity to showcase not only the scale of our tenure, but also the strategic importance of our position alongside MP Materials. With the U.S. Government increasingly focused on securing domestic supply chains for critical minerals, Locksley is well placed to deliver a mine-to-market solution for antimony and rare earths. We look forward to progressing our exploration program and building long-term value for our shareholders.’

*To view tables and figures, please visit:
https://abnnewswire.net/lnk/0SKL75LX

About Locksley Resources Limited:

Locksley Resources Limited (ASX:LKY,OTC:LKYRF) (FRA:X5L) (OTCMKTS:LKYRF) is an ASX listed explorer focused on critical minerals in the United States of America. The Company is actively advancing exploration across two key assets: the Mojave Project in California, targeting rare earth elements (REEs) and antimony. Locksley Resources aims to generate shareholder value through strategic exploration, discovery and development in this highly prospective mineral region.

Mojave Project

Located in the Mojave Desert, California, the Mojave Project comprises over 250 claims across two contiguous prospect areas, namely, the North Block/Northeast Block and the El Campo Prospect. The North Block directly abuts claims held by MP Materials, while El Campo lies along strike of the Mountain Pass Mine and is enveloped by MP Materials’ claims, highlighting the strong geological continuity and exploration potential of the project area.

In addition to rare earths, the Mojave Project hosts the historic ‘Desert Antimony Mine’, which last operated in 1937. Despite the United States currently having no domestic antimony production, demand for the metal remains high due to its essential role in defense systems, semiconductors, and metal alloys. With significant surface sample results, the Desert Mine prospect represents one of the highest-grade known antimony occurrences in the U.S.

Locksley’s North American position is further strengthened by rising geopolitical urgency to diversify supply chains away from China, the global leader in both REE & antimony production. With its maiden drilling program planned, the Mojave Project is uniquely positioned to align with U.S. strategic objectives around critical mineral independence and economic security.

Tottenham Project

Locksley’s Australian portfolio comprises the advanced Tottenham Copper-Gold Project in New South Wales, focused on VMS-style mineralisation

Source:
Locksley Resources Limited

Contact:
Locksley Resources Limited
T: +61 8 9481 0389
E: info@locksleyresources.com.au

News Provided by ABN Newswire via QuoteMedia

This post appeared first on investingnews.com

Barrick Mining (TSX:ABX,NYSE:B) has agreed to sell its Hemlo gold mine in Ontario, Canada, for up to US$1.09 billion, continuing the company’s shift away from non-core assets.

The company announced on Thursday (September 11) that Carcetti Capital (TSXV:CART.H), which will be renamed Hemlo Mining, will acquire the mine under terms that include US$875 million in cash, US$50 million in Hemlo Mining shares and as much as US$165 million in contingent payments tied to future gold prices and production.

Barrick President and Chief Executive Mark Bristow said the sale is part of the company’s ongoing capital allocation approach, noting that proceeds will help bolster the firm’s balance sheet and fund returns to shareholders.

“The sale of Hemlo at an attractive valuation marks the close of Barrick’s long and successful chapter at the mine and underscores our disciplined focus on building value through our Tier One gold and copper portfolio,” Bristow said.

Hemlo, located near Marathon, Ontario, has produced more than 25 million ounces of gold over three decades of continuous operation. The mine transitioned from open-pit to underground operations in 2020.

The incoming Hemlo Mining board will include Robert Quartermain, founder of Pretium Resources and former CEO of SSR Mining (NASDAQ:SSRM,TSX:SSRM). He played a key role in the original discovery of Hemlo while at Teck Resources (TSX:TECK.A,TSX:TECK.B,NYSE:TECK). The company will be led by incoming CEO Jason Kosec, and supported by a consortium that includes Wheaton Precious Metals (TSX:WPM,NYSE:WPM) and Orion Mine Finance.

To finance the acquisition, Hemlo Mining has secured a US$1 billion package comprised of US$400 million in gold streaming from Wheaton, US$415 million in equity and US$200 million in debt.

Wheaton will also take up to US$50 million of the equity raise.

“Hemlo offers a unique opportunity to add immediate, accretive gold ounces from a politically stable jurisdiction, backed by a long history of production and a capable operating team,” said Wheaton CEO Randy Smallwood.

Under the streaming agreement, Wheaton will purchase 13.5 percent of Hemlo’s payable gold until 181,000 ounces are delivered, after which the rate will fall to 9 percent for another 157,330 ounces, and then to 6 percent for the remainder of the mine’s life. Wheaton’s attributable production is expected to average around 20,000 ounces annually for the first decade and more than 17,000 ounces annually over the life of mine, which is forecast to extend for at least 14 years.

For Barrick, the sale continues a multi-year effort to trim smaller, less profitable operations in favor of large, long-life assets that meet its “tier one” criteria. Earlier this year, the company also divested its stakes in Donlin and Alturas, bringing expected gross proceeds from non-core asset sales in 2025 to more than US$2 billion.

While Barrick has emphasized that Canada remains an important exploration jurisdiction, the Hemlo arrangement effectively ends its role as a mine operator in its home country.

Reports of a potential sale had circulated since mid-2024, spurring rumors that Barrick was in advanced talks with Discovery Silver (TSX:DSV,OTCQX:DSVSF) to divest Hemlo; those discussions ultimately did not result in a deal.

Securities Disclosure: I, Giann Liguid, hold no direct investment interest in any company mentioned in this article.

This post appeared first on investingnews.com

Newmont (TSX:NGT,NYSE:NEM,ASX:NEM) is preparing to withdraw from the TSX, the latest in a string of moves to streamline operations and rein in costs following its US$15 billion takeover of Newcrest Mining in 2023.

The Denver-based miner said on Wednesday (September 10) that it has applied for a voluntary delisting of its common shares from the TSX, effective at the close of trading on September 24.

The company cited “low trading volumes” on the Canadian exchange, and said the decision is expected to “improve administrative efficiency and reduce costs for the benefit of Newmont’s shareholders.”

Newmont’s shares will continue to trade on the NYSE, where it maintains its primary listing, as well as on the ASX and the Papua New Guinea Stock Exchange under the ticker symbol NEM.

Rising costs and restructuring plans

Newmont’s all-in sustaining costs reached record levels earlier this year, eroding profits even as bullion prices hit all-time highs above US$3,500 per ounce in April and remained above US$3,300 through most of the summer.

The company has acknowledged that its cost base has outpaced peers.

In the second quarter, Newmont’s costs were nearly 25 percent higher than those of Agnico Eagle Mines (TSX:AEM,NYSE:AEM), a Canadian rival considered one of the industry’s leanest producers.

Newmont’s costs have risen more than 50 percent over the past five years, driven by higher energy, labor and material prices, as well as integration expenses tied to Newcrest’s operations.

CEO Tom Palmer told investors in July that Newmont was pursuing additional measures to lower its expenses.

Behind the scenes, Newmont has been preparing for more aggressive measures.

People familiar with the matter told Bloomberg News that management has set an internal target to lower costs by as much as US$300 per ounce, or roughly 20 percent. Meeting that benchmark could require thousands of layoffs across the company’s global workforce of about 22,000, excluding contractors.

While Newmont has not disclosed the scope of planned reductions, some employees have already been informed of redundancies, according to the report. Managers have also been briefed on potential curbs to long-term incentive programs as part of a broader restructuring. A company spokesperson confirmed earlier this year that Newmont launched a cost and productivity improvement program in February.

Alongside cost cutting, Newmont has moved to divest non-core assets acquired in the Newcrest deal.

Since late 2024, the company has sold multiple Canadian operations: the Eleonore mine for about US$795 million, the Musselwhite mine in Ontario for US$850 million and its stake in the Porcupine operations for US$425 million.

The asset sales are intended not only to cut debt at the company, but also to sharpen its focus on higher-margin operations, particularly in North America and Australia.

Despite higher costs, Newmont shares have surged 95 percent this year; the company also announced a US$3 billion share repurchase program in July.

Securities Disclosure: I, Giann Liguid, hold no direct investment interest in any company mentioned in this article.

This post appeared first on investingnews.com

(TheNewswire)

Vancouver, British Columbia TheNewswire – September 15th, 2025 Prismo Metals Inc. (the ‘ Company ‘ ) (CSE: PRIZ,OTC:PMOMF) (OTCQB: PMOMF) is pleased to report that its exploration team has identified porphyry style mineralization at its Silver King project located outside the town of Superior in Arizona. Given the proximity of the nearby Resolution Copper deposit (a joint venture between Rio Tinto and BHP), the team is excited about the potential of this same style of mineralization identified at surface within the eastern portion of our claim.

This region is world-class for porphyry systems and base and precious metals, and we believe there is significant untapped potential. Our recent field work at the Silver King mine was successful in identifying several exploration targets apart from the historic silver mine deposit including polymetallic veins, manto replacements and a strongly altered intrusion with stockwork quartz-pyrite veining. Identifying this porphyry style mineralization on the claim block is a very positive development ,’ said Dr. Craig Gibson , Chief Exploration Officer.

Figure 1 . Map showing Silver King project and nearby mineral deposits.

The Silver King deposit is located three kilometers from the Resolution Copper deposit and the high-grade Magma mine, a former copper and silver producer, located 0.6 to 1.5 kilometers to the southwest Mineralization at Silver King is hosted by the same rock sequence that hosts those two deposits but is exposed at surface and is not covered by the thick sequence of unmineralized volcanic rocks that covers Resolution Copper. From 1911 to 1996 the Magma mine was developed on veins and replacement deposits in the Paleozoic and Precambrian strata and intrusive rocks, producing approximately 27.6 million short tons of ore averaging about 4.9% copper with important quantities of zinc, gold (689K oz) and silver (34.3M oz) (Briggs, 2015), eventually leading to the discovery of the nearby Resolution copper deposit (Fig. 1).

M ineralization similar to that at the Magma mine is exposed in several historic mine workings with abundant oxide copper minerals, mainly malachite, which were developed along a northeast dipping limestone horizon near the contact with a quartz diorite intrusion and quartzite along the same structural and stratigraphic trend of the Magma mine. The largest occurrence, at the Black Diamond mine in the eastern portion of the claim block, was developed on a large outcrop of abundant specular hematite and malachite replacing a limestone bed (Fig. 2) .

Additionally, an erosional window in a regional quartz diorite has exposed a felsic intrusion to the east of the Silver King workings that was identified in historical records and now confirmed by Prismo geologists.  This felsic intrusion, previously described as a breccia pipe, is characterized by very strong stockwork quartz-pyrite veining in a quartz-sericite altered host rock. This target contains anomalous metal values in soil samples analyzed with the XRF. According to historical reports it has high salinity fluid inclusions typical of a porphyry system, providing evidence for porphyry mineralization on the Silver King claim package.

Figure 2 . Geologic and land map of the Silver King project showing newly described veins in magenta (Ag-Pb-Zn) and green (Cu-Ag) and replacement mineralization in red. The strongly altered intrusion with stock work quartz-pyrite veining is indicated by the crosshatch.

‘Much of the focus of the exploration program to date consisted of a property wide survey of historic mines and prospects surrounding the Silver King workings, said Gordon Aldcorn, President of Prismo .

The exploration work has resulted in the identification of several mineralized occurrences on the property, including veins in the vicinity of the Silver King mine, and replacement and skarn mineralization in limestone units of the sedimentary sequence near the contact.’

Part of the initial exploration program consisted of a reconnaissance survey of the geology and mineral occurrences as well as a geochemical and alteration mineral survey around the surface expression of the Silver King deposit and a second separate target to the east.

The geochemical survey used a handheld XRF instrument to measure soil samples, and showed discrete anomalies for Cu, Ag, and Sb around the historic glory hole, with the copper geochemistry also associated with the ENE striking Cu bearing vein mentioned previously (Fig. 3). Twenty-nine samples have been submitted to the lab, with an additional fifteen samples from the Ripsey mine.

This initial phase of Prismo exploration on the Silver King project is already generating a better understanding of potential with new structures not fully uncovered in historical mining approaches. This work also helps qualify our upcoming drill program which is currently in the permitting stage and is anticipated to be advanced shortly.

Figure 3 . Soil geochemistry maps for Cu, Ag, and Sb from the Silver King mine.  Contours are from values measured in soils by a handheld XRF in the field, with ranges for Cu at 5,619 ppm to 12.5 ppm, Ag at 186 ppm to 1.3 ppm, and Sb at 300 ppm to 3.9 ppm.

Click Image To View Full Size

As previously reported in Primo’s news release of August 28, 2025, the Company geologists identified two previously undescribed veins in the area surrounding the historic glory hole developed on the original exposure of high-grade silver at the Silver King deposit.  Visual inspection and analysis with a handheld XRF show two distinct veins, one with abundant silver lead and zinc and the other with copper and silver values.

Figure 4 . Location of the Company’s projects within the Arizona Copper Belt

Qualified Person

Dr. Craig Gibson, PhD., CPG., a Qualified Person as defined by NI-43-01 regulations and Chief Exploration Officer and a director of the Company, has reviewed and approved the technical disclosures in this news release. The historic data presented in this press release was obtained from public sources, should be considered incomplete and is not qualified under NI 43-101, but is believed to be accurate. The Company has not verified the historical data presented and it cannot be relied upon, and it is being used solely to aid in exploration plans. References to mineralization at the Magma Mine and Resolution Copper deposit is not necessarily indicative of mineralization on the Silver King property.

  1. (2) Briggs, D., 2015, Superior, Arizona: An old mining camp with many lives, Ariz. Geol Survey Contributed Report CR-15-D, 13p.

About the Silver King and Ripsey Mines

Discovered in 1875, the Silver King mine was one of Arizona’s most important historic producers, yielding nearly 6 million ounces of silver at grades of up to 61 oz/t.  The Silver King mine sits only 3 km from the main shaft of the Resolution Copper project — a joint venture between Rio Tinto and BHP and one of the world’s largest unmined copper deposits with an estimated copper resource of 1.787 billion metric tonnes at an average grade of 1.5% copper (1) . The unique land position is fully surrounded by Resolution Copper’s claim block, offering strategic upside. Selected samples from small-scale production in the late 1990s returned grades as high as 644 oz/t silver (18,250 g/t) and 0.53 oz/t gold (15 g/t), indicating that high-grade mineralization remains.

The Ripsey mine is a historic gold-silver-copper producer located about 20 km west of the Hot Breccia project. Historic mine workings consisting of tunnels and shafts on several levels were developed along a vein over about 400 meters of strike length and 160 meters vertically. A small tonnage of mineral was produced by the Optionor in the late 1990’s. Limited sampling by Dr. Craig Gibson from the mine workings has yielded 15.9 g/t gold and 275 g/t silver over 0.75 meters and 8.7 g/t gold, 181 g/t silver, 3% copper and 9% zinc over 1 meter.  No modern exploration has been carried out at the project, providing significant exploration upside and multiple drill targets.

About Prismo Metals Inc.

Prismo (CSE: PRIZ,OTC:PMOMF) is a mining exploration company focused on advancing its Silver King, Ripsey and Hot Breccia projects in Arizona and its Palos Verdes silver project in Mexico.

Please follow @PrismoMetals on , , , Instagram , and

Prismo Metals Inc.

1100 – 1111 Melville St., Vancouver, British Columbia V6E 3V6

Phone: (416) 361-0737

Contact:

Alain Lambert, Chief Executive Officer alain.lambert@prismometals.com

Gordon Aldcorn , President gordon.aldcorn@prismometals.com

Cautionary Note Regarding Forward-Looking Information

This release includes certain statements and information that may constitute forward-looking information within the meaning of applicable Canadian securities laws. Forward-looking statements relate to future events or future performance and reflect the expectations or beliefs of management of the Company regarding future events. Generally, forward-looking statements and information can be identified by the use of forward-looking terminology such as intends’ or anticipates ‘, or variations of such words and phrases or statements that certain actions, events or results may’, could’, should’, would’ or occur’. This information and these statements, referred to herein as ‘forward‐looking statements’, are not historical facts, are made as of the date of this news release and include without limitation, statements regarding discussions of future plans, estimates and forecasts and statements as to management’s expectations and intentions with respect to, among other things: the timing, costs and results of drilling at Hot Breccia.

These forward‐looking statements involve numerous risks and uncertainties, and actual results might differ materially from results suggested in any forward-looking statements. These risks and uncertainties include, among other things: delays in obtaining or failure to obtain appropriate funding to finance the exploration program at Silver King.

In making the forward-looking statements in this news release, the Company has applied several material assumptions, including without limitation, that: the ability to raise capital to fund the drilling campaign at Silver King and the timing of such drilling campaign.

Although management of the Company has attempted to identify important factors that could cause actual results to differ materially from those contained in forward-looking statements or forward-looking information, there may be other factors that cause results not to be as anticipated, estimated or intended. There can be no assurance that such statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements and forward-looking information. Readers are cautioned that reliance on such information may not be appropriate for other purposes. The Company does not undertake to update any forward-looking statement, forward-looking information or financial outlook that are incorporated by reference herein, except in accordance with applicable securities laws. We seek safe harbor.

Copyright (c) 2025 TheNewswire – All rights reserved.

News Provided by TheNewsWire via QuoteMedia

This post appeared first on investingnews.com

(TheNewswire)

VANCOUVER September 12, 2025 TheNewswire – Providence Gold Mines Inc. (‘Providence’ or the ‘Company’) is pleased to announce a non brokered Unit Private Placement Financing of up to $250,000 through the issuance of 5,000,000 units oof the Company (each a ‘Unit’) the (‘Private Placement’). Each Unit will consist of one Common Share and one full Warrant exercisable for a period of two years. The Unit is priced at $0.05 for one Common Share in the Capital of the Company (a ‘Common Share’) and one nontransferable full Warrant. Each nontransferable Warrant will entitle the holder to purchase one additional Common Share at a price of $0.05 for a period of 24 months from the date of closing of the Private Placement will be subject to the approval of the TSXV.

All securities issued with respect to the Private Placement will be subject to a four month plus one day hold period from the date of issuance in accordance with applicable securities laws. Closing of the Private Placement is subject to all necessary regulatory approvals. The Company intends to issue the Units pursuant to the prospectus exemptions set out in National Instrument 45-106- Prospectus Exemptions including the accredited investor exemption and family, friends, and business associates’ exemption.

The Company intends to use funds from the net proceeds for Regulatory Fees, sampling and evaluation of the existing potential underground mineralization at the La Dama De Oro , historical ‘Ace in the Hole stope’ , located near surface, geochemical surface survey and administration

As reported previously, an NI 43 101 has been submitted to the TMX V Exchange for review and approval., The Regulators initial review determined that the submission would be treated as a Fundamental Transaction requiring additional information and the Company is responding accordingly.

Property Summary:

Permits for a Bulk Sample, Water, Road Access, Environmental, Plan of Operation, Mill Site have been approved. To date, there has not been any known drilling or modern-day Scientific exploration or identified NI 43 101 resources.

The La Dama de Oro Property is in the Silver Mountain Mining District, within the structurally complex Eastern California Shear Zone and the intersection with the San Andreas Fault Zone. Bedrock geology includes Mesozoic quartz monzonite that intrudes the Jurassic Sidewinder Volcanics. The structural history of the region implies a sequence of compressional and extensional events that reactivated favorably oriented zones of weakness for the circulation of hydrothermal fluids. The main zone of mineralization is hosted by the La Dama de Oro Fault, a shallow northeast-dipping oblique-slip fault.

The mineralization at the property is classified as a structurally controlled, low-sulfidation epithermal gold-silver vein system. Gold and silver mineralization is associated with multi-phase quartz veining, brecciation, and pervasive hydrothermal alteration along the La Dama de Oro Fault. The largest known vein is 4.5 feet at its widest point and remains open to exploration for over 6,000 feet. The gold system has robust potential not just within the La Dama de Oro vein, but as well for additional undiscovered veins along the fault system.

Ronald A. Coombes, President & CEO commented; ‘having all permits in place gives certainty to realize potential future opportunity for production at the La Dama de Oro mine .

The scientific and technical information contained in this news release has been reviewed and approved by Zachary Black, SME-RM, a Qualified Person as defined under NI 43-101. Mr. Black is a consultant and is independent of Providence Gold Mines Inc.

For more information, please contact Ronald Coombes, President, and CEO directly at

6047242369.

Ronald A. Coombes, President & CE

Phone: 604 724 2369

roombes@providencegold.com

CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING INFORMATION

Neither the OTCQB and or the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.

All statements, trend analysis and other information contained in this press release relative to markets about anticipated future events or results constitute forward-looking statements. All statements, other than statements of historical fact, included herein, including, without limitation, statements relating to the permitting process, future production of Providence Gold Mines, budget and timing estimates, the Company’s working capital and financing opportunities and statements regarding the exploration and mineralization potential of the Company’s properties, are forward-looking statements. Forward-looking statements are subject to business and economic risks and uncertainties and other factors that could cause actual results of operations to differ materially from those contained in the forward- looking statements. Important factors that could cause actual results to differ materially from Providence Gold Mines expectations include fluctuations in commodity prices and currency exchange rates; uncertainties relating to interpretation of drill results and the geology, continuity and grade of mineral deposits; the need for cooperation of government agencies and native groups in the exploration and development of properties and the issuance of required permits; the need to obtain additional financing to develop properties and uncertainty as to the availability and terms of future financing; the possibility of delay in exploration or development programs and uncertainty of meeting anticipated program milestones; and uncertainty as to timely availability of permits and other governmental approvals. Forward-looking statements are based on estimates and opinions of management at the date the statements are made. Providence Gold Mines does not undertake any obligation to update forward-looking statements except as required by applicable securities laws. Investors should not place undue reliance on forward-looking statement

Copyright (c) 2025 TheNewswire – All rights reserved.

News Provided by TheNewsWire via QuoteMedia

This post appeared first on investingnews.com

Investor Insight

Cardiol Therapeutics is positioned with a late-stage lead asset, multiple orphan indications, strong clinical proof-of-concept data, and a differentiated non-immunosuppressive approach to inflammatory heart disease. The company’s 2025–2026 catalysts – MAVERIC Phase III enrollment progress, full ARCHER data, and CRD-38 clinical initiation – are key value drivers in large and underserved cardiovascular markets.

Overview

Cardiol Therapeutics Inc. (NASDAQ:CRDL,TSX:CRDL) is a clinical-stage life sciences company focused on the research, development, and commercialization of innovative anti-inflammatory and anti-fibrotic therapies for the treatment of heart disease. The company’s programs target serious, often life-threatening cardiovascular conditions for which there are limited or no approved treatments, including recurrent pericarditis, acute myocarditis, and heart failure.

Cardiol’s therapeutic approach centers on modulating inflammasome pathway activation—a central driver of inflammation and fibrosis in the heart. This is achieved through pharmaceutically manufactured cannabidiol formulations developed under cGMP standards. Cannabidiol has been shown in preclinical and clinical studies to down-regulate inflammatory mediators (e.g., IL-1, IL-6) and preserve cardiac structure and function, offering the potential for disease-modifying, non-immunosuppressive treatment options.

The company’s lead oral drug candidate, CardiolRx, is in late-stage clinical development:

  • Phase II ARCHER trial for acute myocarditis, a leading cause of sudden cardiac death in people under 35.

Cardiol is also advancing CRD-38, a proprietary subcutaneous cannabidiol formulation for heart failure. IND-enabling studies are underway following compelling preclinical results showing cardioprotection through preservation of mitochondrial function and prevention of cardiac remodeling.

Company Highlights

  • Clinical-stage life sciences company developing therapies for heart disease.
  • Late-Stage Pipeline: Lead oral drug candidate, CardiolRx, in the ongoing Phase III MAVERIC trial for recurrent pericarditis (RP).
  • Strong Market Potential: Current US revenue for third-line RP therapy is approximately $500 million, with analyst forecasts’ exceeding $1 billion by 2028.
  • Validated Target: Focused on inflammasome activation, implicated in multiple cardiac conditions.
  • World-class Collaborations: Long-standing collaborations and partnerships with leading international cardiovascular research centers.
  • Near-term Milestones – Advance MAVERIC Phase III enrollment (50% targeted H2 2025, full enrollment H1 2026); present full Phase II ARCHER trial results for acute myocarditis in H2 2025; complete IND-enabling work and initiate Phase I for CRD-38 in heart failure.

Key Projects

MAVERIC Program – Recurrent Pericarditis

What it is: A pivotal clinical program testing CardiolRx in patients with recurrent pericarditis, a painful and debilitating inflammation of the membrane around the heart that often returns despite prior treatments. The condition can cause severe chest pain, shortness of breath, and repeated hospitalizations.

Why it matters: Current third-line therapy is costly, immunosuppressive and associated with a high recurrence rate after discontinuation. CardiolRx offers the potential for a non-immunosuppressive, disease-modifying option.

Status:

  • Completed MAvERIC-Pilot Phase II: Rapid and durable reductions in pain and inflammation sustained over 26 weeks; majority of patients recurrence-free during extension.
  • Phase III MAVERIC trial: Multinational, double-blind, placebo-controlled study enrolling 110 high-risk patients across ~20 sites in North America and Europe. Primary endpoint: recurrence-free rate at 24 weeks after IL-1 blocker discontinuation.

ARCHER Trial – Acute Myocarditis

What it is: A global Phase II trial evaluating CardiolRx in acute myocarditis, an inflammatory heart muscle disease and a major cause of sudden cardiac death in people under 35.

Why it matters: There are no FDA- or EMA-approved drugs for acute myocarditis. Current care is supportive, and many patients develop chronic heart problems.

Status:

  • Enrolled 109 patients at 34 sites across five countries; completed in Q4 2024.
  • Topline results (Q3 2025) showed notable improvements in heart muscle health (extracellular volume, LV mass) and confirmed safety/tolerability.
  • Full results to be presented at a scientific meeting in H2 2025.

Heart Failure Program – CRD-38

What it is: Development of a subcutaneous cannabidiol formulation for heart failure, including heart failure with preserved ejection fraction (HFpEF), a condition with limited treatment options and high mortality.

Why it matters: Heart failure affects over 64 million people globally, with high hospitalization and death rates; inflammation and fibrosis play key roles in disease progression.

Status:

  • IND-enabling studies underway; Phase I trial planned after regulatory submission.
  • Preclinical research shows CRD-38 protects heart muscle cells, preserves mitochondrial function, and prevents remodeling and inflammation.

Management Team

David Elsley – President, Chief Executive Officer, and Director

David Elsley is the founder and former president and CEO of Vasogen. He has more than 30 years’ experience developing, financing, and managing corporate development of life sciences companies.

Dr. Andrew Hamer – Chief Medical Officer and Head of Research and Development

Dr. Andrew Hamer has an MBChB degree. Hamer is the former executive director at Amgen, responsible for leading global development of Repatha®. Hamer is the former chief cardiologist at Nelson Hospital, New Zealand. He has over 19 years of experience practicing cardiology and internal medicine.

Chris Waddick – Chief Financial Officer and Director

Chris Waddick has an MBA degree, is a chartered professional accountant, and is a certified management accountant. Waddick has over 30 years of experience in financial and executive roles in the biotechnology and energy industries. Waddick is the former chief financial officer and chief operating officer of Vasogen Inc.

Bernard Lim – Chief Operating Officer

Bernard Lim has over 30 years of experience in the life sciences industry, spanning biotechnology, diagnostics, medical devices, and high-technology companies. Lim is the founder and CEO of a highly successful drug delivery company that he led from research and development through to commercialization, and facilitated its eventual acquisition by Eli Lily. Lim is a chartered engineer per UK standards and is a member of the Institution of Engineering and Technology.

Andrea B. Parker – Senior Director of Clinical Operations

Dr. Andrea Parker is the former chief scientific officer at Peter Munk Cardiac Center, University Health Network. Parker is a clinical epidemiologist with more than 30 years’ experience in clinical trials design, management, and execution in industry and academic settings.

John A. Geddes – Vice-President, Corporate Development

John Geddes has over 25 years of experience in the healthcare industry, comprising roles within pharmaceutical, biotechnology, clinical diagnostics, and life science research technology companies. Geddes has an MBA degree and is the former corporate senior director of business development at Luminex Corporation, a DiaSorin Company.

Anne Tomalin – Director of Regulatory and Quality

Anne Tomalin is the founder of CanReg and TPIreg, regulatory firms previously sold to Optum Insight and Innomar Strategies, respectively. Tomalin is an expert in regulatory affairs in Canada, the United States, and Europe.

Board of Directors

Guillermo Torre-Amione – Chairman

Guillermo Torre-Amione is the president of TecSalud academic medical center and school of the Instituto Tecnológico y de Estudios Superiores de Monterrey (ITESM), Mexico. Torre-Amione is the former director of Cardiac Transplantation at the Houston Methodist DeBakey Heart & Vascular Center.

Jennifer M. Chao – Director

Jennifer M. Chao has over 25 years of experience in the biotech and life sciences industries focused primarily on finance and corporate strategy. Chao is managing partner of CoreStrategies Management, a company she founded in 2008 to provide transformational corporate and financial strategies to biotech/life science companies for maximizing core valuation.

Peter Pekos – Director

Founder of Dalton Pharma, Peter Pekos has broad experience in research, development, and commercialization of pharmaceuticals, products, and services.

Colin Stott – Director

Colin Stott has over 30 years of experience in pre-clinical and clinical development, with specific expertise in the development of cannabinoid-based medicines. Stott is the chief operating officer of Alterola Biotech Inc. and the former scientific affairs director, international, and research and development operations director for GW Pharmaceuticals, a world leader in the development of cannabinoid therapeutics.

Teri Loxam – Director

Teri Loxam has over 25 years of experience in the pharmaceutical, life sciences and TMT industries with diverse roles spanning strategy, investor relations, finance and communications. Loxam is chief financial officer of Compass Pathways plc (Nasdaq:CMPS), a biotechnology company dedicated to accelerating patient access to evidence-based innovation in mental health.

Timothy Garnett – Director

Timothy Garnett is the chair of Ophirex and director of Maplight Therapeutics. He is a pharmaceutical industry executive with over 30 years’ experience, including two decades at Eli Lilly and Company, where he served as Chief Medical Officer from 2008 until his retirement in 2021. During his tenure at Eli Lilly, he led the successful development of therapeutics in women’s health, endocrinology, and neuroscience, resulting in multiple commercial launches globally.

Scientific Advisory Board

Dr. Paul Ridker is director of the Center for Cardiovascular Disease Prevention, a translational research unit at Brigham and Women’s Hospital in Boston (BWH). A cardiovascular medicine specialist, he is also the Eugene Braunwald Professor of Medicine at Harvard School of Medicine (HSM). Ridker received his medical degree from HSM and then completed an internal medicine residency and a cardiology fellowship at BWH. He is board certified in internal medicine. Ridker’s clinical interests include coronary artery disease and the underlying causes and prevention of atherosclerotic disease. He is the author of over 900 peer-reviewed publications and reviews, 64 book chapters, and six textbooks related to cardiovascular medicine.

Dr. Bruce McManus is a professor emeritus of the Department of Pathology and Laboratory Medicine at the University of British Columbia. He has served as CEO of the Center of Excellence for Prevention of Organ Failure (PROOF Center), director of the UBC Center for Heart and Lung Innovation, and scientific director of the Institute of Circulatory and Respiratory Health, CIHR. McManus received BA and MD degrees from the University of Saskatchewan, an MSc from Pennsylvania State University, and a PhD from the University of Toledo. McManus pursued post-doctoral fellowships at the University of California, Santa Barbara in environmental physiology and at the National Heart, Lung, and Blood Institute in Bethesda. McManus served as MD in cardiovascular and pulmonary pathology, and completed residency training at the Peter Bent Brigham Hospital, Harvard University, in Internal Medicine and Pathology.

Dr. Joseph Hill is a professor of internal medicine and molecular biology, chief of cardiology at UT Southwestern Medical Center, in Dallas, and is the director of the Harry S. Moss Heart Center. Hill holds both the James T. Willerson, MD, distinguished chair in cardiovascular diseases, and the Frank M. Ryburn Jr. Chair in Heart Research. He graduated from Duke University with an MD and a PhD in 1987. Hill’s PhD dissertation research was in the field of cardiac ion channel biophysics. He then worked for five years as a postdoctoral fellow at the Institut Pasteur in Paris, studying central and peripheral nicotinic receptors. He next completed an internal medicine internship and residency, as well as a clinical cardiology fellowship, at the Brigham and Women’s Hospital, Harvard Medical School.

This post appeared first on investingnews.com

Gold’s record-setting price run continued this week, with yet another new all-time high in the books. Silver also fared well, breaking US$42 per ounce.

According to Bloomberg, gold has now also surpassed its inflation-adjusted all-time high of US$850 per ounce, which it set more than 45 years ago on January 21, 1980. The news outlet notes that at the time the US was dealing with currency issues, inflation and recession concerns.

These are problems that sound all too familiar today. This week brought the release of the latest US consumer price index (CPI) data, which shows a 0.4 percent month-on-month increase for the all-items index — that’s ahead of estimates and the most since the start of 2025.

Meanwhile, core CPI, which excludes the food and energy categories, was up 0.3 percent from July. On an annual basis, core CPI was up 3.1 percent, while overall CPI rose 2.9 percent.

US producer price index (PPI) data also came out this week.

The index, which measures costs at a wholesale level, showed an unexpected 0.1 percent month-on-month decrease for August; the result was the same for core PPI.

Attention is now shifting to the US Federal Reserve’s next meeting, which is set to run from September 16 to 17. For weeks now the central bank has been widely expected to cut interest rates, and experts believe this week’s CPI and PPI numbers support that idea.

“Today’s CPI may appear to offset yesterday’s PPI, but it wasn’t hot enough to distract the Fed from the softening jobs picture. That translates into a rate cut next week — and, likely, more to come’ — Ellen Zentner, Morgan Stanley Wealth Management

CME Group’s (NASDAQ:CME) FedWatch tool now shows odds of 93.9 percent for a 25 basis point cut, while the likelihood of a 50 basis point reduction stands at 6.1 percent.

Bullet briefing — Mining majors in mega M&A, Newmont to exit TSX

Anglo, Teck to merge in US$53 billion deal

Anglo American (LSE:AAL,OTCQX:AAUKF) and Teck Resources (TSX:TECK.A,TSX:TECK.B,NYSE:TECK) announced that they plan to merge in a US$53 billion transaction.

The new entity, which the companies say will be one of the world’s largest copper producers, will have assets in Canada, the US, Latin America and Southern Africa.

Its primary listing will be in London, but its headquarters will be in Canada — a commitment that Teck CEO Jonathan Price told BNN Bloomberg will be ‘perpetual.’ In a bid to safeguard its critical minerals sector, Canada said last year that it will only greenlight foreign takeovers of large critical minerals miners in ‘exceptional circumstances.’

The companies expect annual pre-tax synergies of about US$800 million by the end of the fourth year following the completion of the arrangement.

Experts say the zero-premium, all-share tie up is the second largest mining deal ever, and the biggest in more than a decade. It comes not long after other high-profile M&A attempts involving both companies — Teck rejected a bid from (LSE:GLEN,OTC Pink:GLCNF) in 2023, and Anglo turned down an offer from BHP (ASX:BHP,NYSE:BHP,LSE:BHP) last year.

Newmont to delist from TSX

While the Anglo-Teck deal puts Canada front and center, major miner Newmont (TSX:NGT,NYSE:NEM,ASX:NEM) is backing away from the northern nation. The company said it has applied to voluntarily delist its shares from the TSX amid low volumes.

Newmont also said the move will help boost administrative efficiency and reduce expenses. The firm has faced increasing costs since acquiring Newcrest Mining in 2023, and sources familiar with the matter recently told Bloomberg that it’s looking to lower costs by around 20 percent.

Newmont will retain its primary listing in New York, as well as listings in Australia and Papua New Guinea. Its TSX delisting is expected to be effective on September 24.

Barrick to sell Hemlo for US$1.09 billion

Also making a move away from Canada this week was Barrick Mining (TSX:ABX,NYSE:B), which has agreed to sell its Hemlo gold mine to Carcetti Capital (TSXV:CART.H) for US$1.09 billion.

Located in Ontario, Hemlo has operated for 30 years, producing over 21 million ounces of gold during that time. The sale comes as Barrick divests non-core assets and pivots toward copper.

The company put Hemlo up for sale earlier this year, and in July was rumored to be selling the operation to Discovery Silver (TSX:DSV,OTCQX:DSVSF); that deal ultimately didn’t pan out.

Carcetti will be renamed Hemlo Mining once the transaction closes, and is expected to uplist from the TSX Venture Exchange’s NEX Board. Its backers include Robert Quartermain, who is known for leading SSR Mining (TSX:SSRM,NASDAQ:SSRM) and Pretium Resources.

Securities Disclosure: I, Charlotte McLeod, hold no direct investment interest in any company mentioned in this article.

This post appeared first on investingnews.com